


No Accounting Records, No Choice: Business Expenses Are Deductible in the Year of Payment
Court of Cassation, First Chamber, 18 June 2026, F.25.0070.N
The Facts
In February 2008, a company director provided a personal guarantee for a €25,000,000 loan taken out by her company, up to a maximum amount of €8,750,000. At the time, she performed her duties as a director without remuneration.
In late 2013, the guarantee was called upon. She paid €8,379,562.10 to the creditor and, by operation of Articles 2028 and 2029 of the former Civil Code, was subrogated to the creditor’s rights against the company.
On 28 September 2017, the company was dissolved and its liquidation was closed immediately, with a deficit. The director’s claim for reimbursement became irrecoverable. It was at this point that the taxpayer claimed a deduction for the amount in assessment year 2018, carrying forward the remaining balance to 2019 and 2020. Her reasoning was based on prudence: until the liquidation had been closed, the loss could not be considered certain.
The tax authorities disallowed the deduction.
The Antwerp Court of First Instance dismissed the taxpayer’s claim on the grounds that the requirement relating to the purpose of the expense had not been met. The Court of Appeal upheld the rejection, but on entirely different grounds: the tax period to which the expense should be attributed.
The Court of Appeal first ruled out the application of Article 53, 15°, of the Belgian Income Tax Code 1992 (BITC 92), which allows an individual to assume a company’s losses only where the director makes a payment to the company and the company uses the entire amount to offset its losses. None of these conditions was met: no loss had been taken over, the money had been paid not to the company but to a third party, and it had not been used to make good anything at all.
The general rules of Article 49 therefore applied. This point is often overlooked, even though it governs the entire analysis that follows.
The Decision
The Court of Cassation began by recalling that Article 49, paragraph 2, of the BITC 92 provides two routes to deductibility: expenses actually paid or incurred during the taxable period, or expenses that have acquired the character of certain and liquid debts or losses and have been recorded as such in the accounts.
The appellate judges found that the taxpayer did not keep accounting records and that there was no indication she was required to do so. The second route was therefore unavailable to her.
The Court derived two principles from this.
First, for a taxpayer who is not required to keep accounting records and who, in the absence of such records, cannot record a debt as certain and liquid, the right to deduct an expense arises in the taxable period in which the expense was actually and unconditionally paid.
Second, the fact that the guarantor, once payment has been made, holds a right of recourse against the principal debtor, whether in their own right or by subrogation, does not detract from the actual and unconditional nature of that payment.
The deduction must therefore be claimed in the year of payment.
A Consequence Without Remedy
The deduction should have been claimed for assessment year 2014, corresponding to income year 2013. By the time the tax authorities notified the taxpayer of the adjustment in October 2020, all applicable deadlines had expired.
Consequently, the €8,379,562.10 could no longer be deducted in any assessment year: not in assessment year 2014, because the deduction had not been claimed in time, and not in assessment year 2018, because it had been claimed for the wrong assessment year.
Practical Implications
Where no accounts are kept, it is the payment to the creditor that gives rise to the right to deduct, not the extinction of the recourse claim. The deduction must therefore be claimed in the year in which payment is made, even if the outcome of the recourse against the company remains uncertain. That uncertainty is precisely what the Court regards as irrelevant.
Uncertainty as to whether the guarantee was provided for professional purposes does not justify postponing the deduction. A rejection based on the purpose of the expense can be challenged, whereas a missed statutory deadline cannot be remedied.
One possible alternative lies in accounting law, but this requires particular caution. Article III.82, § 1, paragraph 2, 1°, of the Belgian Code of Economic Law expressly exempts individuals whose self-employed professional activity consists of holding one or more directorships from the obligation to keep accounting records. As a general rule, a company director who provides a guarantee is therefore limited to the first route under Article 49, paragraph 2: the year of payment, and that year alone.
However, the second route may not necessarily be closed. Article 49, paragraph 2, does not make its application conditional upon a statutory obligation to keep accounting records. It requires only that the expenses have acquired the character of certain and liquid debts or losses and have been recorded as such in the accounts.
A company director who voluntarily maintains proper accounting records and records the debt in those accounts in a timely manner could therefore potentially rely on this provision. The judgment does not resolve this question: it concerns a taxpayer who did not keep accounting records. Where there is uncertainty as to the assessment year in which a deduction should be claimed, appropriate legal and tax advice can help identify the necessary adjustments and ensure their proper implementation.
Discover more about this topic?
I am looking for a specialist in





See more articles
30.10.2026
•Tax Law, Andersen in Belgium
Ex officio taxation: No “surprise” income without prior notice of adjustment
In its judgment of 8 May 2026, the Court of Cassation reaffirmed an important limitation on the tax authorities’ power to impose an assessment ex officio: where a taxpayer is assessed ex officio for failing to respond to a notice of adjustment, the assessment may only be based on income already identified in that notice. The tax authorities cannot introduce additional income that the taxpayer has never had an opportunity to challenge.
30.10.2026
•Tax Law, Event
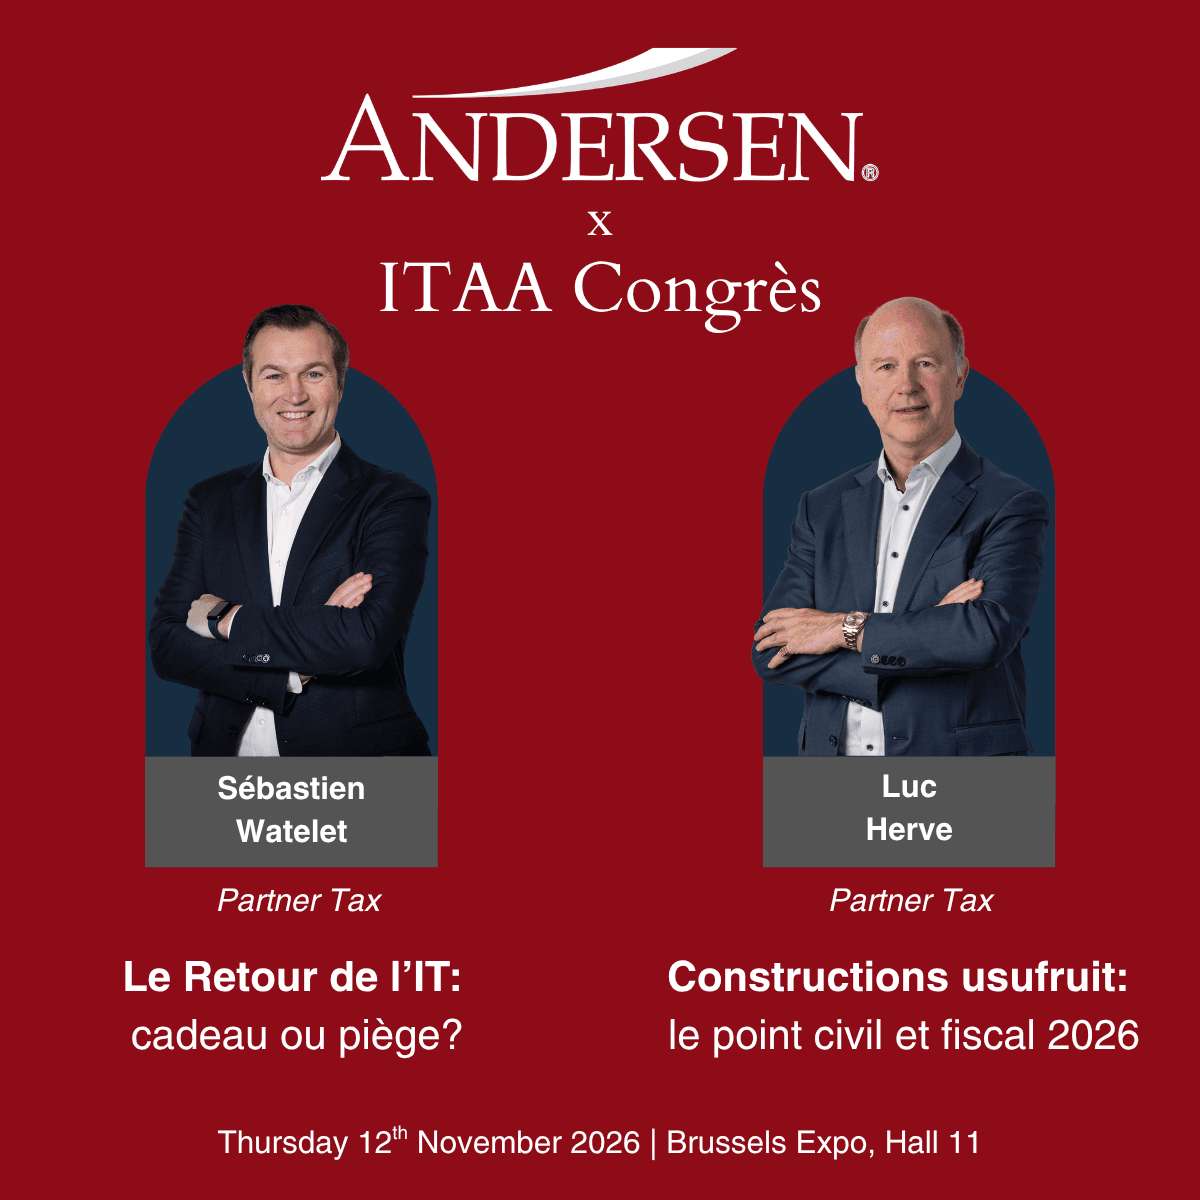
Andersen Partners Sébastien Watelet and Luc Hervé to Speak at ITAA Congress 2026
On 12 November 2026, our Partners Sébastien Watelet and Luc Hervé will each deliver an Expert Conference at the ITAA Congress 2026, taking place at Brussels Expo.
28.10.2026
•Real Estate, Renting and Co-ownership, Event
The status of the real estate agent: 15 potential pitfalls examined
On the 15th of April 2027 Legal Learning is hosting a webinar taught by two of our Real Estate partners. It regards the updated Code of Conduct of the Professional Institute of Real Estate Agents, which entered into force on October 1, 2026.
08.10.2026
•Employment Law, Andersen in Belgium
New Laws and Recent Figures: What Are the Implications for Employers in Belgium?
Recent updates to the definition of cross-border workers and changes to Belgian Criminal Law reveal consequences that are relevant for employers. Meanwhile, new figures reveal valuable insight on the job market.