


A Preview for the Real Estate and Construction Sector Based on the Coalition Agreement
The 2025-2029 coalition agreement provides for several measures relevant to the real estate and construction sector. Below, we highlight some key points.
1. A More Favorable Tax Regime for Renovation Works
The federal government intends to permanently apply the reduced VAT rate of 6% for demolition and reconstruction projects to property developers and construction promoters. This measure aims to prevent developers and promoters from reverting to the 21% VAT rate after the transitional arrangement expires on June 30, 2025. Additionally, the scope of application will be expanded to include deliveries, meaning purchases in redevelopment projects by promoters. However, the surface area criterion for such deliveries will be tightened from 200 m² to 175 m², meaning the habitable area must not exceed 175 m² to qualify for the reduced rate.
To support renovations, renovation works on existing (private) homes will continue to benefit from the reduced VAT rate of 6%. However, the property must be at least 10 years old, and the renovations must meet specific criteria. This preferential regime only applies to work carried out by a contractor—self-purchased materials will still be subject to the 21% VAT rate. This fiscal relief allows older properties to be made more energy-efficient at an attractive rate.
Another significant tax reform is the reduction of registration duties for the purchase of a primary residence from 3% to 2%, offering a substantial financial benefit for buyers.
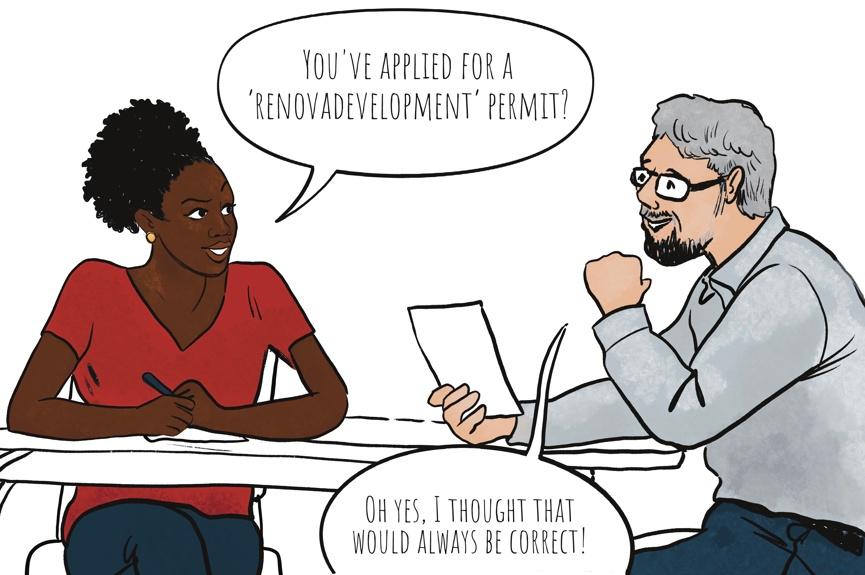
2. The Definition of ‘Renovation Work’ versus ‘Redevelopment’
Uncertainties persist regarding the classification of a project as renovation or redevelopment. This distinction is crucial, as it has major implications. Historically, renovation works often qualified for a reduced VAT rate of 6%, whereas redevelopment projects were generally subject to the 21% rate. Additionally, the revision periods vary significantly—5 years for renovations versus 15 to 25 years for redevelopment projects.
The new government will work on drafting a clear and unambiguous definition of ‘renovation work’ and ‘redevelopment.’ Consideration will also be given to introducing a ‘sustainability condition’ under forthcoming European regulations, while ensuring that administrative burdens for the sector do not increase.
3. Reforms in the Association of Co-Owners (VME/ACP)
Several reforms are planned for the Association of Co-Owners (“VME”), aimed at lowering barriers to energy-efficient renovations and the installation of renewable energy sources such as solar panels.
Firstly, the decision-making process in co-owned apartment buildings for energy-related investments will be adjusted—requiring only a simple majority instead of the previous two-thirds majority. This change will make the decision-making process within VMEs faster and more efficient.
Secondly, the federal government will encourage “VMEs” to develop long-term investment plans for climate-related upgrades and will explore ways to facilitate access to credit for such investments.
4. Reform of the Breyne Law
The Breyne Law, which protects consumers in the purchase of off-plan or newly built homes, will be modernized to provide a higher level of consumer protection. Currently, certain legal loopholes disadvantage consumers.
The reforms will focus on strengthening enforcement by
- economic inspection authorities,
- optimizing professional bans,
- establishing a full-fledged Ombuds service for the construction sector, and
- increasing awareness of existing consumer assistance tools such as Justban.
Additionally, after consultation with industry stakeholders and consumer organizations, a statutory protection regime will be introduced for shell construction and major renovation projects. Currently, these types of projects fall outside the scope of the Breyne Law.
While these reforms aim to achieve commendable goals, the sector fears an increase in administrative burdens. To address these concerns, close consultation with the industry and consumer organizations will play a crucial role.
The experts at Andersen will closely monitor future regulations on your behalf. Be sure to subscribe to our newsletter to stay informed on matters affecting your sector. Don’t hesitate to contact them via info@be.Andersen.com or +32 (0)2 747 40 07.

Discover more about this topic?
I am looking for a specialist in






See more articles
18.11.2026
•Urban Planning and Environmental Law, Real Estate, Renting and Co-ownership, Andersen in Belgium
Court of Justice Sets Limits on Brussels Airbnb Rules, Relaxation to Follow in 2027
A prior authorisation scheme for short-term rentals is not contrary to EU law, but only if it is truly necessary and the procedure provides the operator with sufficient safeguards. This was the ruling of the Court of Justice of the European Union (CJEU) on 22 October 2026 in the Smartflats case. It is now up to the Brussels Court of Appeal to determine whether the Brussels system meets these criteria. In the meantime, more flexible rules will enter into force on 1 January 2027.
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.

03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.