


Building on a Residual Plot? New Rules Make It Easier from 20 August 2026
In recent years, developing a small or awkwardly shaped plot located in a residential reserve area has often proved difficult because of requirements that are simply not workable for such plots, such as a mix of functions or the clustering of dwellings. From 20 August 2026, the Verzameldecreet Omgeving introduces a number of specific relaxations, with clear surface-area thresholds.
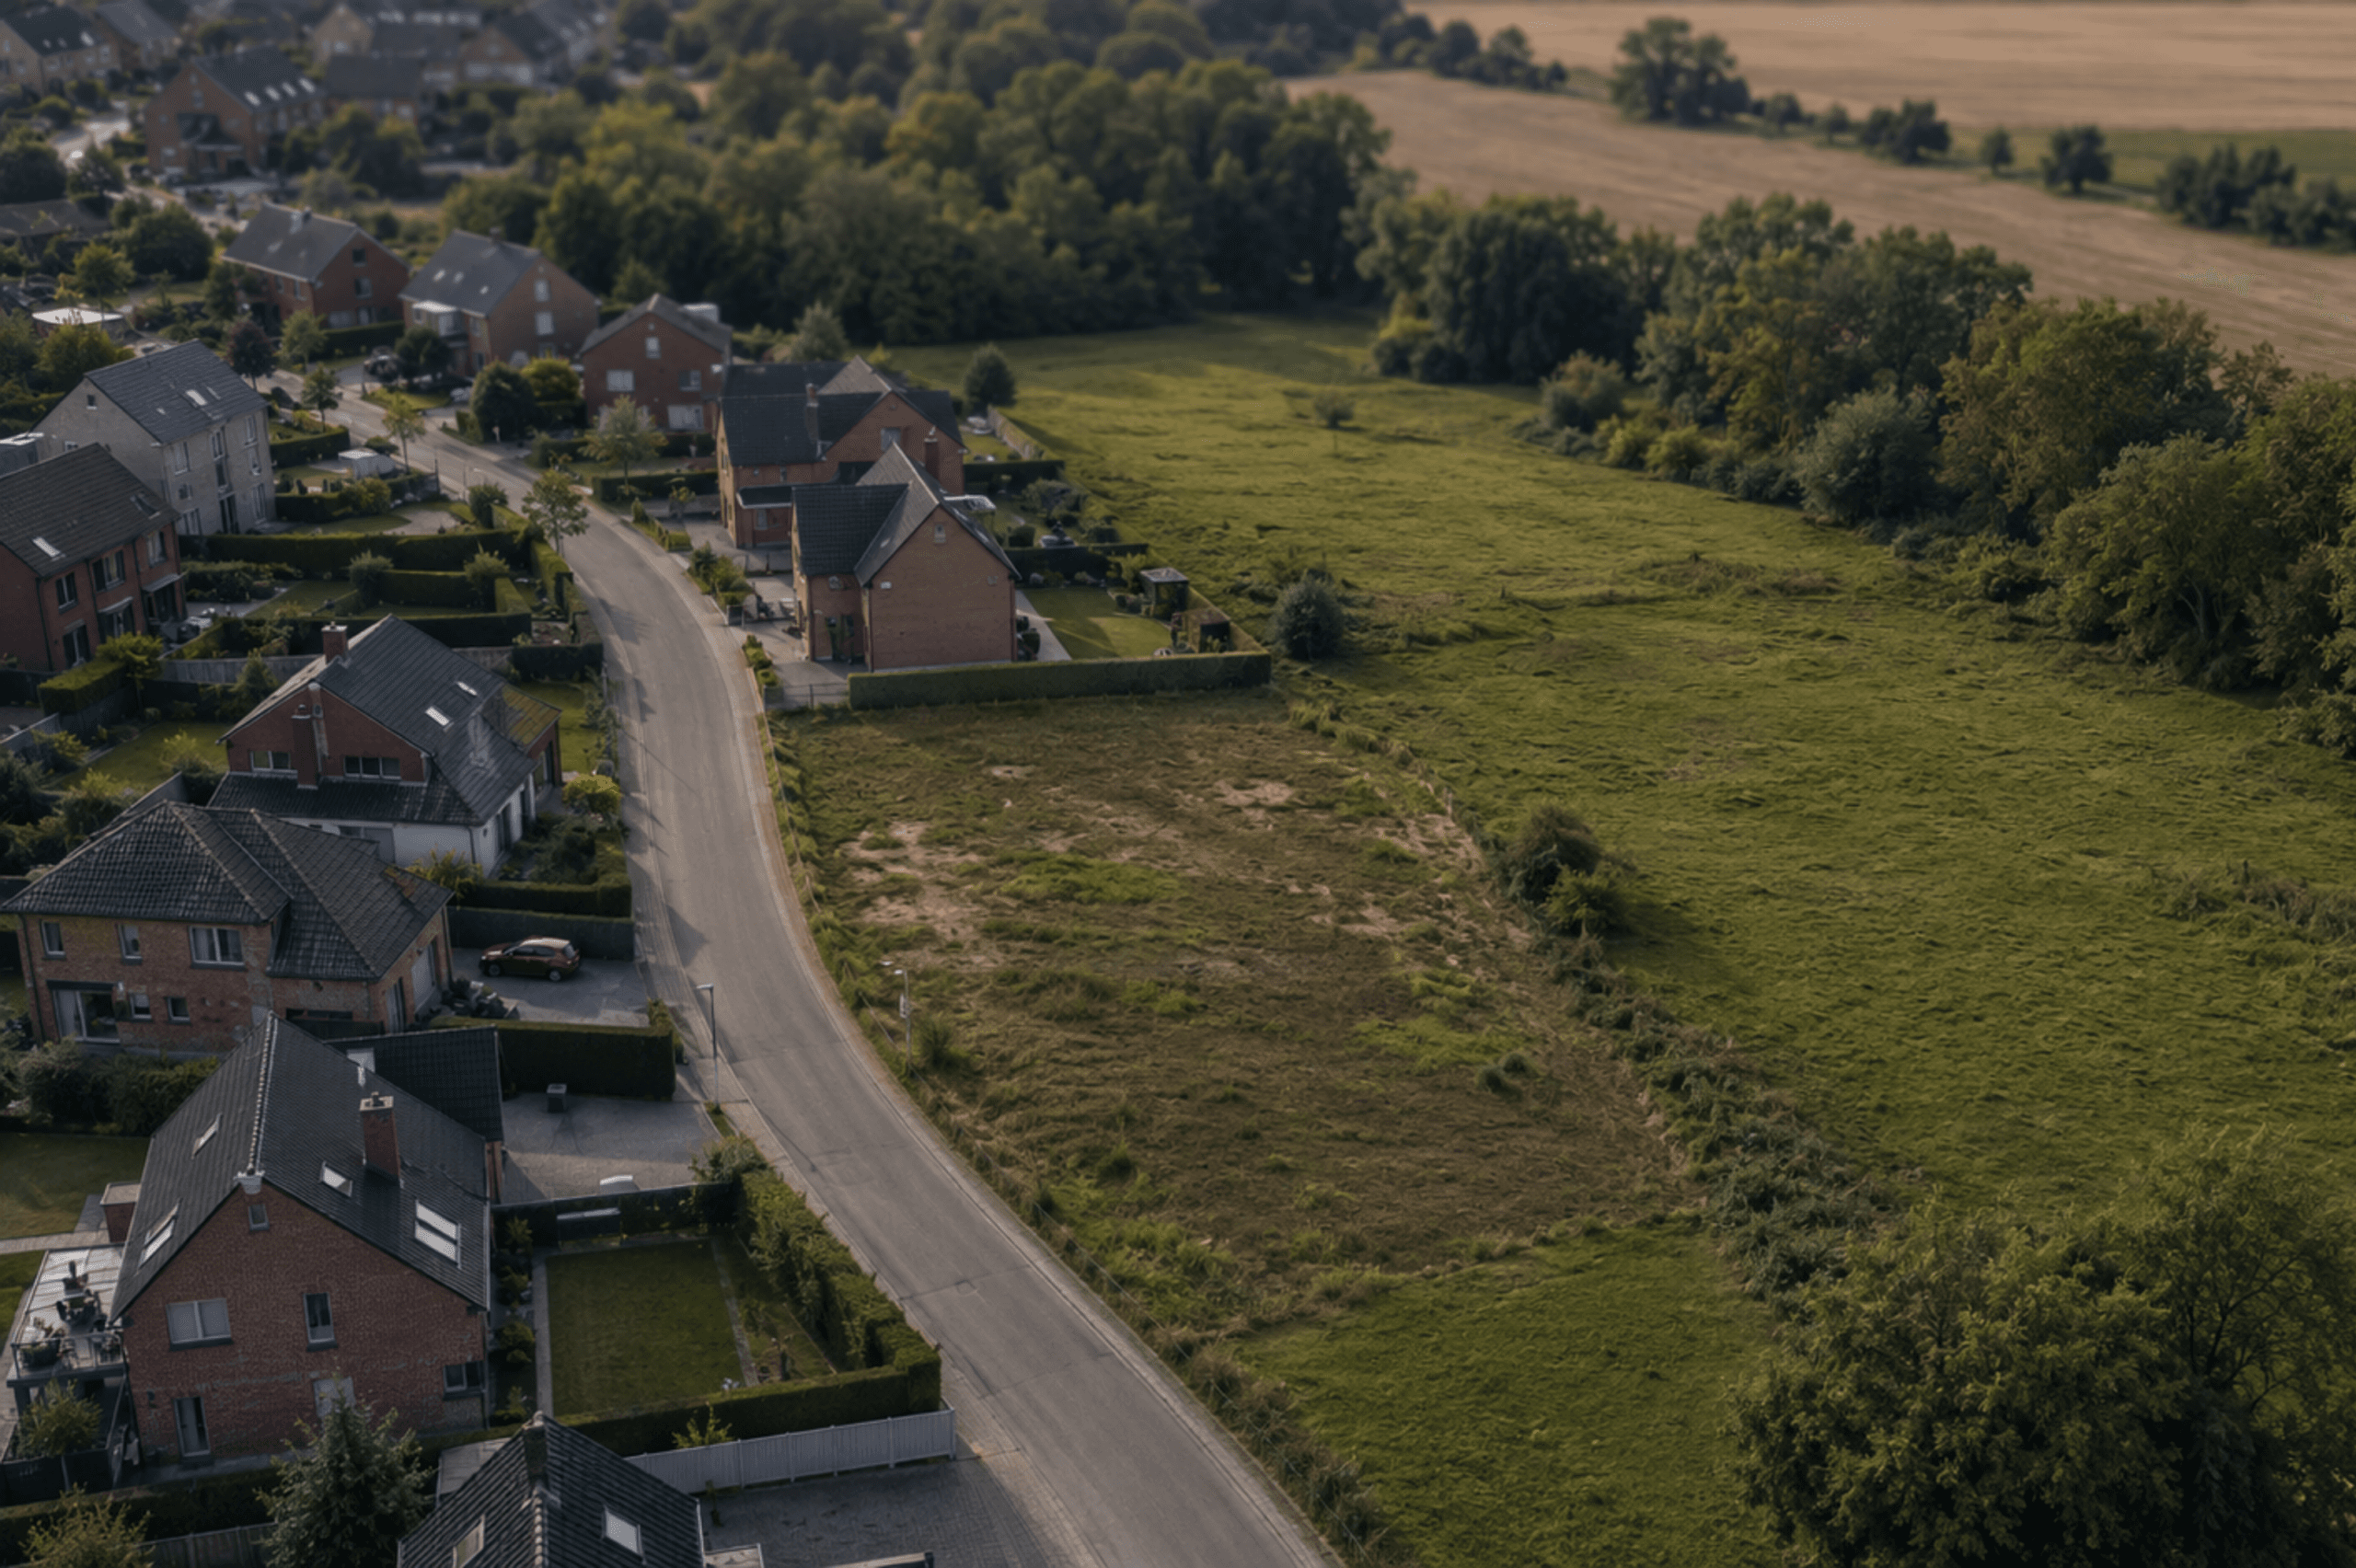
What is a residential reserve area?
Residential reserve area is an umbrella term for several categories of land that, in addition to ordinary residential areas, may still provide scope for housing, but only following an express decision by the municipality.
The best-known and most common category is the residential expansion area (zone d’extension d’habitat / woonuitbreidingsgebied). Even if you are not familiar with the term residential reserve area, you may therefore already be familiar with residential expansion areas.
Why is a release decision required?
Land located in a residential reserve area may only be developed once the municipality has adopted a release decision. This allows the municipality to retain control over which land is developed and when.
As a rule, four requirements must be met when an area is released:
- Mix of functions: the new dwellings may not form a purely residential development. There must also be scope for other functions, such as shops, offices or green spaces.
- Minimum clustering of dwellings: the dwellings must be developed with a certain degree of cohesion, for example as terraced housing or a small subdivision, rather than as scattered detached houses.
- Shared facilities: residents must share certain facilities, such as an access road, parking facilities or a play area, rather than each dwelling having separate facilities of its own.
- High spatial efficiency: the land must be used as efficiently as possible, with a sufficient number of dwellings per hectare, rather than an inefficiently low development density.
The challenge for small plots and residual plots
These requirements make sense when developing a larger area, but they can be unworkable for a small residual plot enclosed by plots that have already been developed.
When the rules were introduced in 2023, an initial proposal to fully exempt residual plots from the requirement to obtain a release decision was ultimately not retained. This followed an opinion of the Council of State pointing to a conflict with the case law of the Constitutional Court concerning changes to zoning provisions.
As a result, even very small residual plots had to comply with the same stringent requirements as an entire subdivision.
Two new exemptions from the release-decision requirement
The Decree adds two situations to Article 5.6.10 of the Flemish Code for Spatial Planning (VCRO) in which no release decision is required:
- An environmental permit solely for the demolition of a structure or the felling of trees;
- A permit for the subdivision of land where the subdivision regulations themselves provide that the part located in a residential reserve area may not be built on or surfaced.
More flexible requirements depending on surface area
Where a release decision remains necessary, a new paragraph 3/1 of Article 5.6.11 VCRO introduces two clear surface-area thresholds:
- Below fifteen ares, i.e. 1,500 m²: a reasoned derogation may be granted from both the requirements relating to high spatial efficiency and the clustering of dwellings, and those relating to a mix of functions and shared facilities.
- Between fifteen ares and half a hectare: a derogation may still be granted from the requirements relating to a mix of functions and shared facilities, but not from the requirements relating to spatial efficiency and the clustering of dwellings.
- Above half a hectare: all requirements continue to apply in full.
Any derogation must always be duly reasoned, taking into account, among other things, the facilities and residential density in the surrounding area.
In addition, the release must still concern a coherent and spatially distinct part of the residential reserve area. Plots may therefore not be artificially subdivided in order to fall below the applicable thresholds.
What does this mean for you?
Do you own a residual plot or a smaller plot in a residential reserve area that, until now, appeared impossible to develop because of the strict requirements? Or are you planning a subdivision that is partly located in a residential reserve area without intending to build on that part?
If so, it may be worth reassessing your file from 20 August 2026 onwards.
Our Real Estate Team would be happy to advise you on permitting and development matters.
Discover more about this topic?
I am looking for a specialist in




See more articles
18.11.2026
•Urban Planning and Environmental Law, Real Estate, Renting and Co-ownership, Andersen in Belgium
Court of Justice Sets Limits on Brussels Airbnb Rules, Relaxation to Follow in 2027
A prior authorisation scheme for short-term rentals is not contrary to EU law, but only if it is truly necessary and the procedure provides the operator with sufficient safeguards. This was the ruling of the Court of Justice of the European Union (CJEU) on 22 October 2026 in the Smartflats case. It is now up to the Brussels Court of Appeal to determine whether the Brussels system meets these criteria. In the meantime, more flexible rules will enter into force on 1 January 2027.
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.

03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.