


The end of the EUR 150 customs duty exemption: the European Union introduces a flat-rate EUR 3 duty on small parcels
Since 1 July 2026, low-value imports from third countries have been subject to a new customs regime. Council Regulation (EU) 2026/382 of 11 February 2026, amending Council Regulation (EC) No 1186/2009 as regards the removal of the customs duty relief based on a value threshold, abolishes the customs duty exemption that previously applied to consignments with an intrinsic value of less than €150. At the same time, it introduces, on a transitional basis, a flat-rate customs duty of €3 per item in certain situations. This reform constitutes one of the first components of the comprehensive overhaul of the EU Customs Union launched by the European Commission to adapt customs rules to the rapid expansion of global e-commerce.
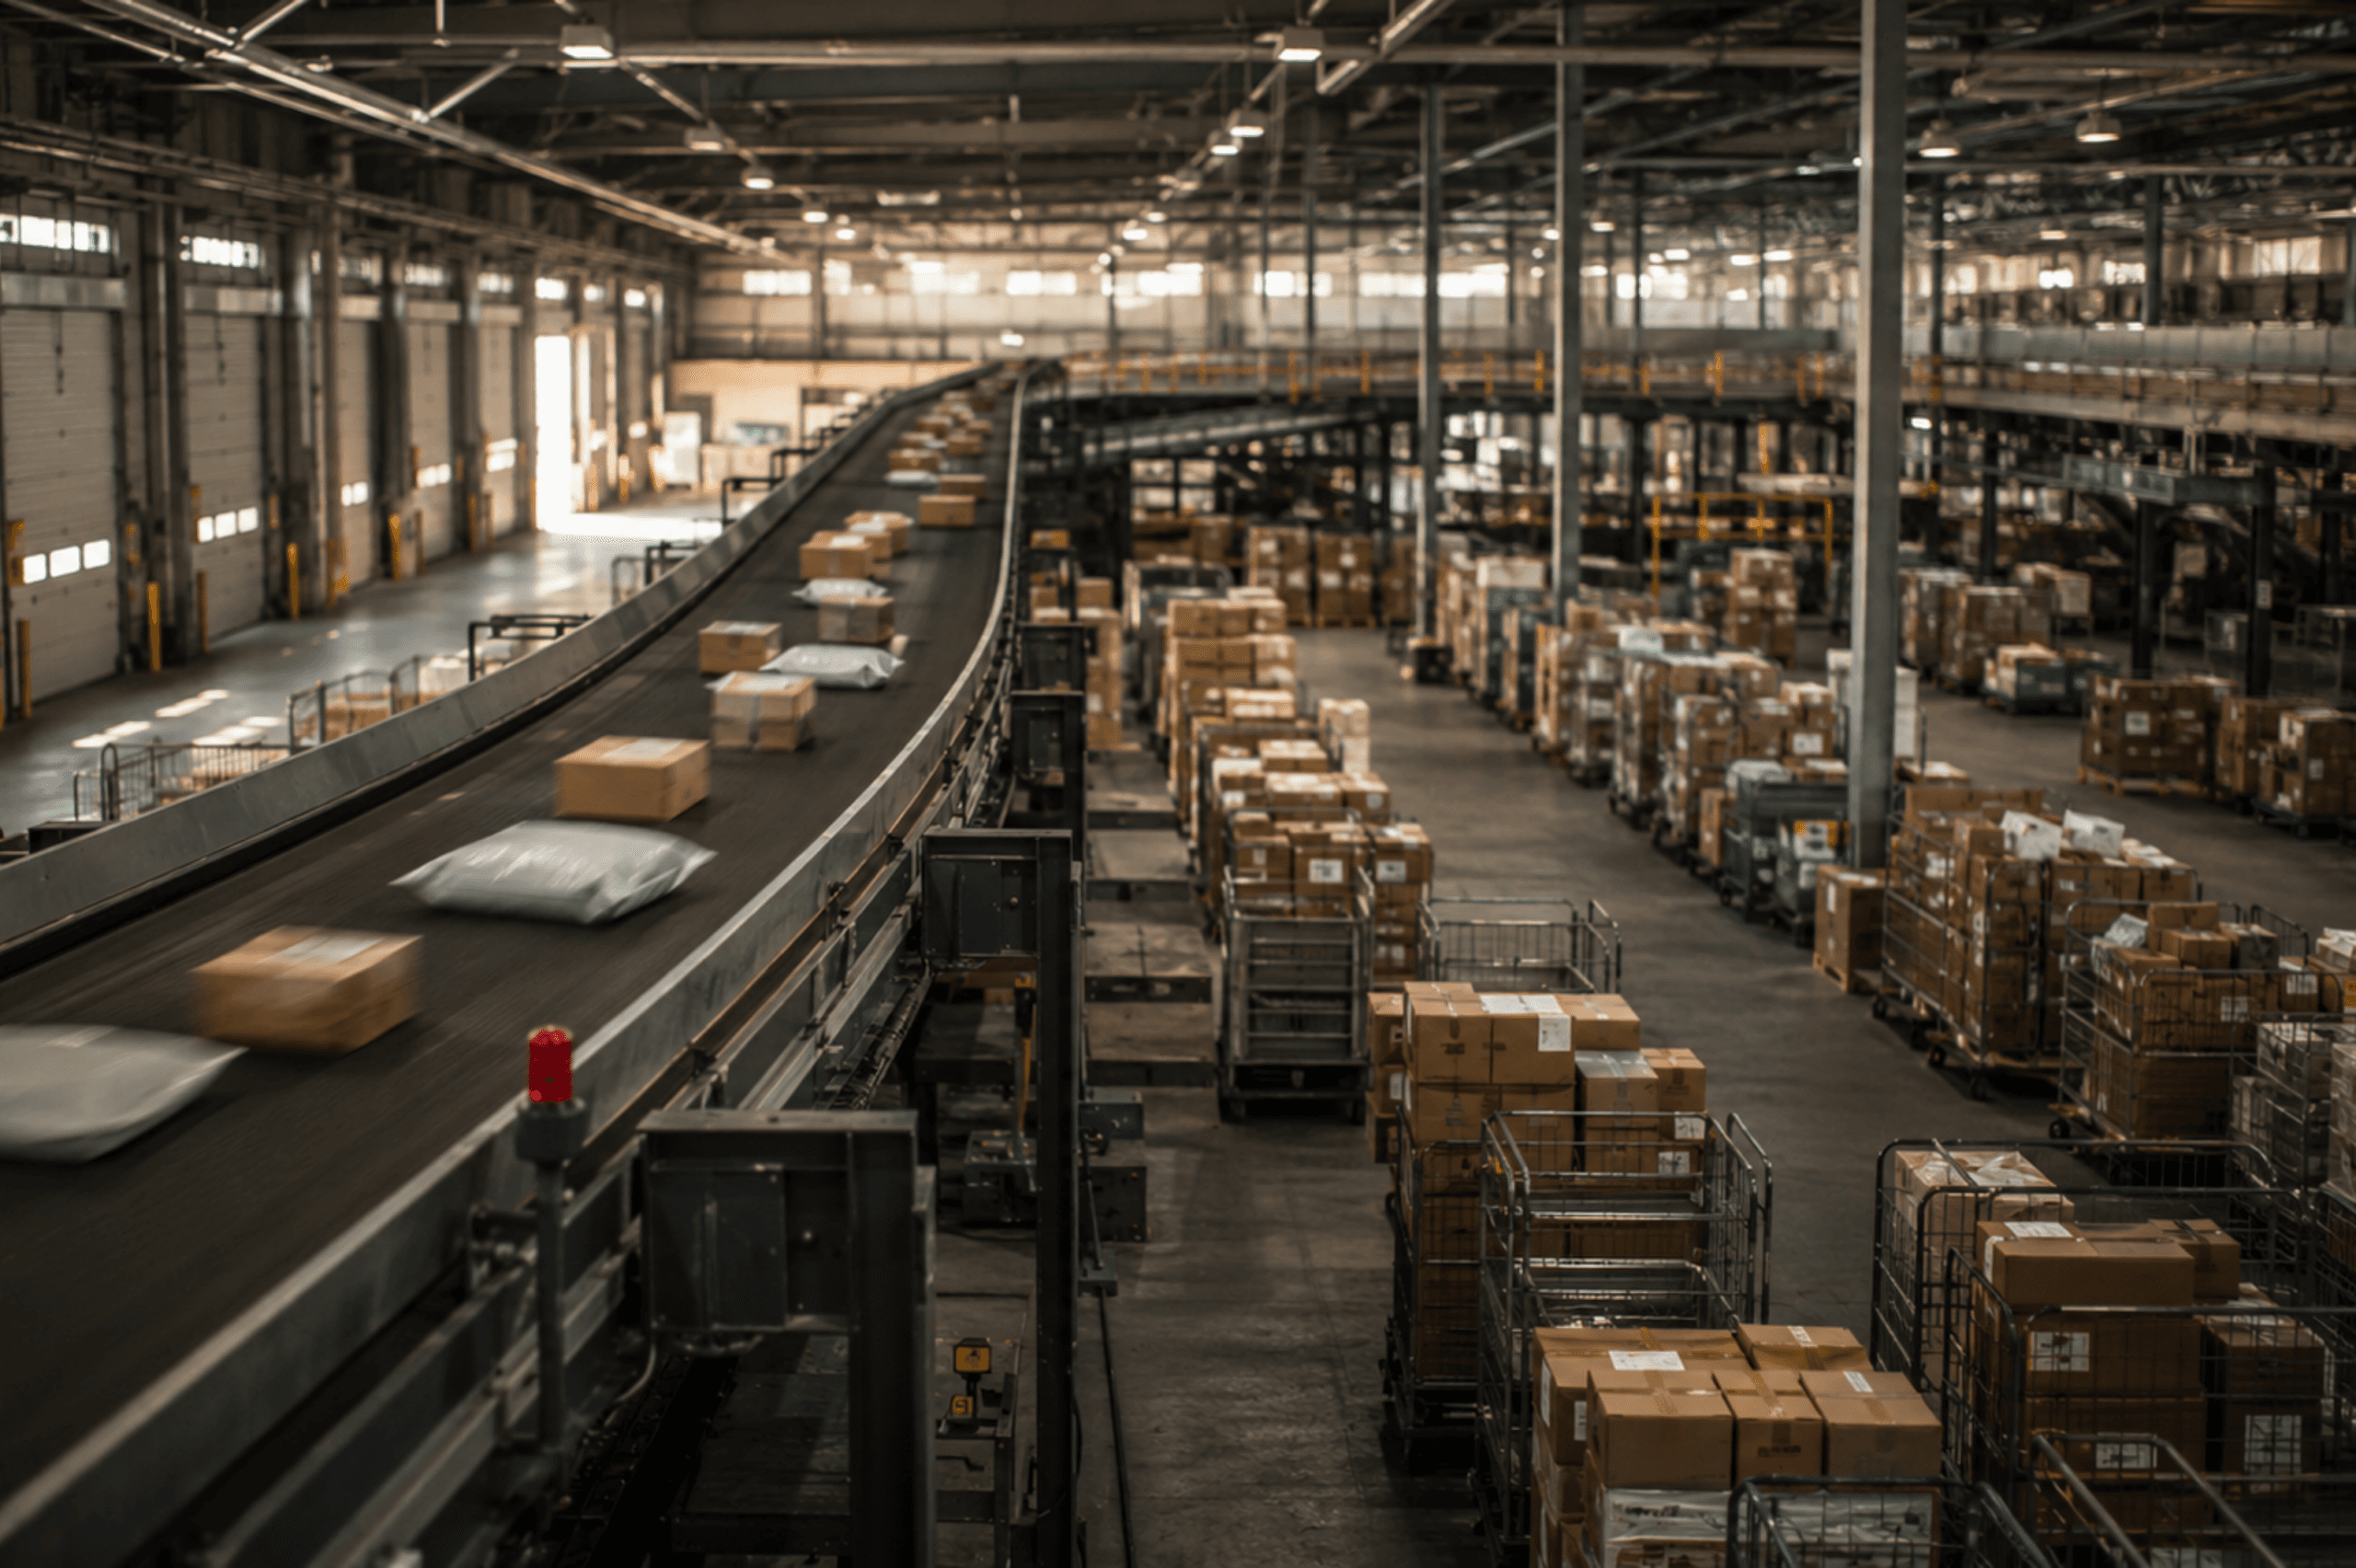
The measure was prompted by the sharp increase in low-value imports, mainly from e-commerce platforms established outside the European Union. Every year, billions of small parcels cross the Union’s borders, creating an unprecedented administrative burden for customs authorities. According to the EU legislator, the previous regime also encouraged practices such as undervaluing goods or artificially splitting consignments in order to keep each parcel below the €150 threshold and thereby avoid customs duties.
This development follows the reform of the VAT rules for e-commerce, which entered into force on 1 July 2021 and abolished the VAT exemption for consignments valued at less than EUR 22. Against that background, maintaining the EUR 150 customs duty exemption had become increasingly difficult to justify. The Council also notes that the digitalisation of customs procedures and the availability of electronic data for all imports mean that an exemption, originally introduced to avoid a disproportionate administrative burden, is no longer necessary. Conversely, the need to protect the financial interests of the European Union and its Member States, together with the objective of ensuring fairer competition between EU businesses and sellers established in third countries, now justifies the systematic collection of customs duties on these imports.
The Regulation therefore removes the exemption laid down in Regulation (EC) No 1186/2009. However, pending the entry into force of the future Union Customs Code and its new centralised IT infrastructure, the EU legislature has introduced a transitional regime to avoid excessive administrative complexity. Accordingly, from 1 July 2026 until 1 July 2028, a flat-rate customs duty of €3 per item applies to goods contained in postal consignments whose total intrinsic value does not exceed €150, in particular where they fall under the Import One Stop Shop (IOSS) scheme or are transported through postal services.
It should be emphasised, however, that this €3 charge is not a new general import tax, but rather a simplified and temporary customs duty intended to facilitate the processing of the vast number of small parcels entering the European Union. The Regulation also provides for a prompt review of this measure in order to assess any diversion of trade flows and to determine whether it should remain in force beyond 2028 if the new European customs infrastructure is not yet fully operational.
Beyond its budgetary impact, this reform reflects a broader policy objective of restoring a level playing field between businesses established within the European Union and sellers from third countries, while simultaneously strengthening the effectiveness of customs controls in response to the rapid growth of cross-border e-commerce. It therefore represents an important milestone in the modernisation of the EU Customs Union and foreshadows the fully digital customs system that the European Union intends to implement progressively.
Discover more about this topic?
I am looking for a specialist in






See more articles
08.09.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
Flanders Cracks Down on Substandard Housing with Significantly Higher Fines
Are you renting out a home with serious quality defects? If so, you risk criminal prosecution. Starting today, penalties for renting substandard housing in Flanders will be significantly increased. A fine can reach up to 800,000 euros under aggravating circumstances. At the same time, judges will have greater discretion to tailor the penalty to the severity of the offense.

08.09.2026
•Corporate Law and M&A, Andersen in Belgium
Belgium transposes the Women on Boards Directive: a further step towards more balanced corporate governance
On 18 July 2026, the Council of Ministers approved, at second reading, the preliminary draft law transposing Directive (EU) 2022/2381, better known as the Women on Boards Directive. The Directive aims to address the underrepresentation of women on the boards of listed companies and to promote equal opportunities in the appointment of directors. According to the European legislator, a balanced representation of women and men not only contributes to achieving the principle of equality, but also supports better decision-making, stronger corporate governance and greater economic competitiveness.

04.09.2026
•Urban Planning and Environmental Law, Andersen in Belgium
Faster Permitting Process in Brussels?
The Brussels-Capital Region aims to process urban planning permits and certificates more quickly going forward. A new circular sets ambitious deadlines for Urban, the regional administration for urban planning and heritage. However, these are internal targets, not new legal deadlines. If they are not met, this will not, in itself, affect your permit or certificate application.

03.09.2026
•Corporate Law and M&A, Andersen in Belgium
Belgium takes a first step towards digital European company law
On 3 July 2026, the Belgian federal Council of Ministers approved a preliminary draft law which, among other things, transposes a first component of Directive (EU) 2025/25 into Belgian law. This concerns the obligation to subject the incorporation documents and amendments to the articles of association of a general partnership (VOF/SNC) or limited partnership (CommV/SComm) to prior administrative, judicial or notarial review.